

Key Messages
- Small Enterprise Administration (SBA) loans include cost-saving options, akin to aggressive charges and waived upfront warranty charges for certified SBA Categorical debtors, together with service-disabled veterans.
- Service-disabled veterans can compete for devoted federal contract {dollars} after pursuing SBA certification.
- Grants, or monetary help that doesn’t must be repaid, are generally designed for service-disabled veterans.
- Many veteran-focused mortgage applications join service-disabled veteran debtors to coaching, mentorship, and counseling.
In search of the correct financing for a veteran-owned enterprise? From working capital to industrial actual property, CDC Small Enterprise Finance provides mortgage choices for eligible small companies. Join with our lending group to be taught extra.
Service-disabled veterans who wish to begin a enterprise can entry numerous applications and funding choices. As an example, by way of the Small Enterprise Administration and different companions, service-disabled veteran-owned small companies can qualify for loans, grants, and specialised coaching that present each capital and steerage. Right here’s a take a look at the very best applications and enterprise loans for disabled veterans and tips on how to apply.
Why Help for Service-Disabled Veteran Entrepreneurs Issues
Whereas veterans personal greater than 1.6 million small companies nationwide, many face distinctive challenges when getting began, from navigating service-related disabilities to securing startup capital and adapting army abilities to the enterprise world.
Discovering help might help bridge the hole between a veteran’s army service and civilian success. That help could come by way of entry to reasonably priced lending and advising companies from nonprofits. These assets empower veterans to construct sustainable careers, strengthen native economies, and proceed serving their communities by way of entrepreneurship.
High Small Enterprise Loans for Service-Disabled Veterans
Beginning or rising a enterprise typically requires capital. Listed below are some veteran enterprise loans service-disabled veterans can make the most of.
1. SBA 7(a) Loans
The 7(a) mortgage is the SBA’s hottest program and gives funding as much as $5 million for small companies. Service-disabled veteran enterprise house owners can use mortgage funds for working capital, actual property purchases, enterprise debt refinancing, and a variety of different initiatives.
7(a) compensation phrases rely upon using proceeds.
| Use of Proceeds | Most Compensation Time period* |
|---|---|
| Working Capital | As much as 10 years |
| Gear | As much as 10 years (generally as much as 15 years) |
| Actual Property | As much as 25 years |
*There may be particular exceptions. Attain out to our mortgage officers to see what’s out there.
The SBA 7(a) Group Benefit mortgage provides loans from $30,000 to $350,000 for startups and current companies. Funds can be utilized for working capital, working bills, tenant enhancements, tools, enterprise acquisitions, and refinancing enterprise debt.
Whereas 7(a) loans aren’t created particularly for veterans, lots of the SBA’s insurance policies profit companies which might be veteran-owned.
For instance, the SBA 7(a) Group Benefit program allows Group Benefit Small Enterprise Lending Firms, akin to CDC Small Enterprise Finance, to assist enterprise house owners with restricted assets, together with veterans, entry credit score extra simply.
The Categorical mortgage, one other kind of seven(a) mortgage, waives the upfront price for honorably discharged, service-disabled veterans and their spouses.
2. SBA 504 Mortgage
The SBA 504 mortgage program is designed to advertise financial improvement. Along with assembly the final mortgage standards, a enterprise should present it meets the SBA’s job creation or public coverage targets.
Companies can meet this requirement by creating or retaining not less than one job for each $95,000 in SBA-backed debenture funding they borrow by way of a 504 mortgage, and qualifying small-manufacturer or energy-policy initiatives have a $150,000-per-job commonplace.
The 504 debenture borrowing limits go as much as $5.5 million with phrases of 10, 20, or 25 years. The funds can be utilized to buy massive belongings, enhance amenities and land, or repay qualifying debt (usually debt initially used to buy actual property or massive belongings like heavy equipment).
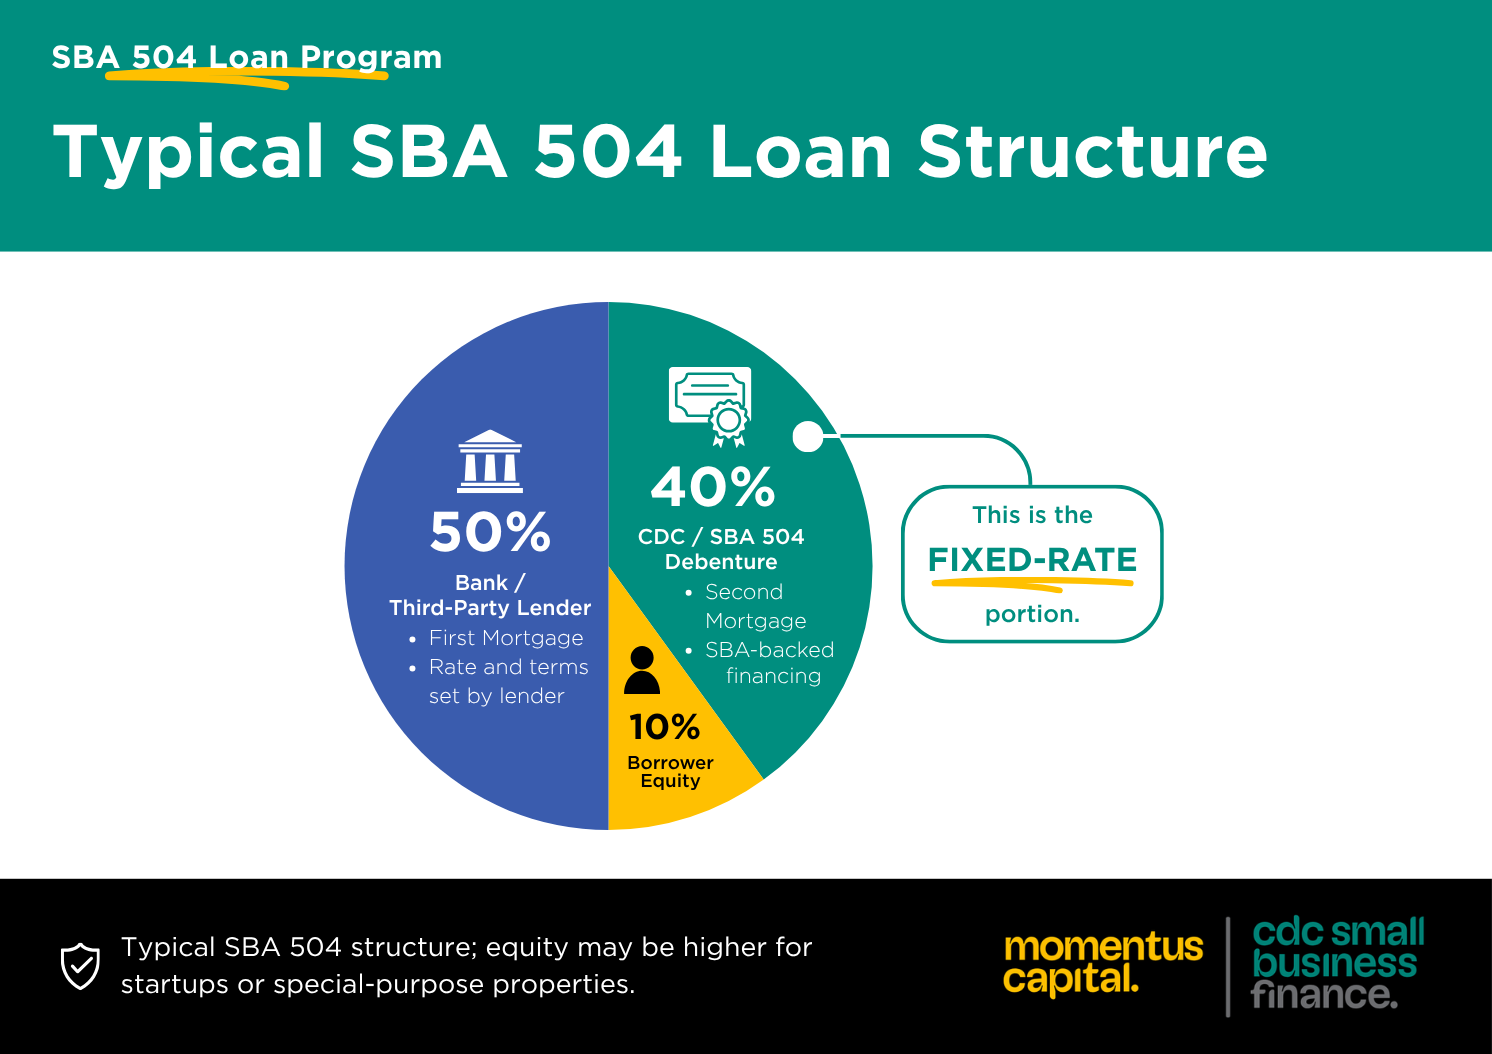
Service-disabled veteran enterprise house owners can apply for a 504 mortgage with a taking part Licensed Improvement Firm (CDC), akin to CDC Small Enterprise Finance. A typical 504 mission consists of financing of fifty % or extra from a third-party lender, as much as 40 % from the SBA-backed CDC debenture, and not less than 10 % from the enterprise. The minimal borrower contribution rises to fifteen % for brand new companies or restricted/special-purpose property and 20 % when each apply.
3. Impower 95 Mortgage
Some companies could not qualify for a 504 mortgage due to owner-occupancy necessities, citizenship necessities, or down fee issues. In these instances, the Impower 95 mortgage, a particular program supplied by Momentus Direct Capital, an affiliate of CDC Small Enterprise Finance, could assist. The Impower 95 mortgage can be utilized to buy industrial actual property with as much as 95 % financing and has no minimal credit score rating.
The streamlined course of lets companies get preapproved in as little as two weeks after submitting a accomplished software, and so they could select interest-only repayments to get began.
4. SBA Microloans
The Microloan is one other SBA lending program. It’s typically ideally suited for startups or companies with smaller funding wants. Since many lenders haven’t any down fee necessities, it will possibly scale back a enterprise’s upfront lending prices. Borrowing quantities high out at $50,000 with phrases as much as seven years.
SBA Microloans can be used for a wide range of functions that assist small companies increase, akin to working capital, stock, provides, and equipment or tools. Nonetheless, proceeds from a microloan can not be used to pay current money owed or to buy actual property.
Service-disabled veteran enterprise house owners can apply for a Microloan by way of taking part intermediaries, that are usually nonprofit neighborhood lenders like CDC Small Enterprise Finance. These intermediaries deal with the applying course of and distribute the loans. Additionally they usually present training and different assets to debtors. For instance, our Enterprise Advising Providers provides free enterprise advising to mortgage candidates.
5. Army Reservist Financial Damage Catastrophe Mortgage (MREIDL)
The Army Reservist Financial Damage Catastrophe Mortgage falls below the SBA’s catastrophe mortgage program. If a key workers member is a army reservist who is named to energetic responsibility, the MREIDL gives funding to assist the enterprise cowl working bills. A service-disabled veteran may gain advantage from this program, for example, in the event that they make use of a reservist who will get referred to as to energetic responsibility.
Mortgage quantities can go as much as $2 million, however the SBA determines every borrower’s restrict based mostly on the enterprise’s precise financial harm. Compensation phrases may be as much as 30 years, and loans above $50,000 require collateral.
Companies don’t want a lender to use for an MREIDL. As an alternative, they’ll undergo the SBA’s Catastrophe Help Portal.
Exploring small enterprise financing?
CDC Small Enterprise Finance helps eligible veteran entrepreneurs discover financing choices to begin, buy, or develop a enterprise. Contact our group to debate out there mortgage choices.

